Introduction
Would you believe me if I told you that one of the easiest ways to improve your finances might have nothing to do with budgeting, saving or investing? What if I told you that you can do this without spending a single dollar? If you’ve already read the title of this blog post then you already know where I’m going with this.
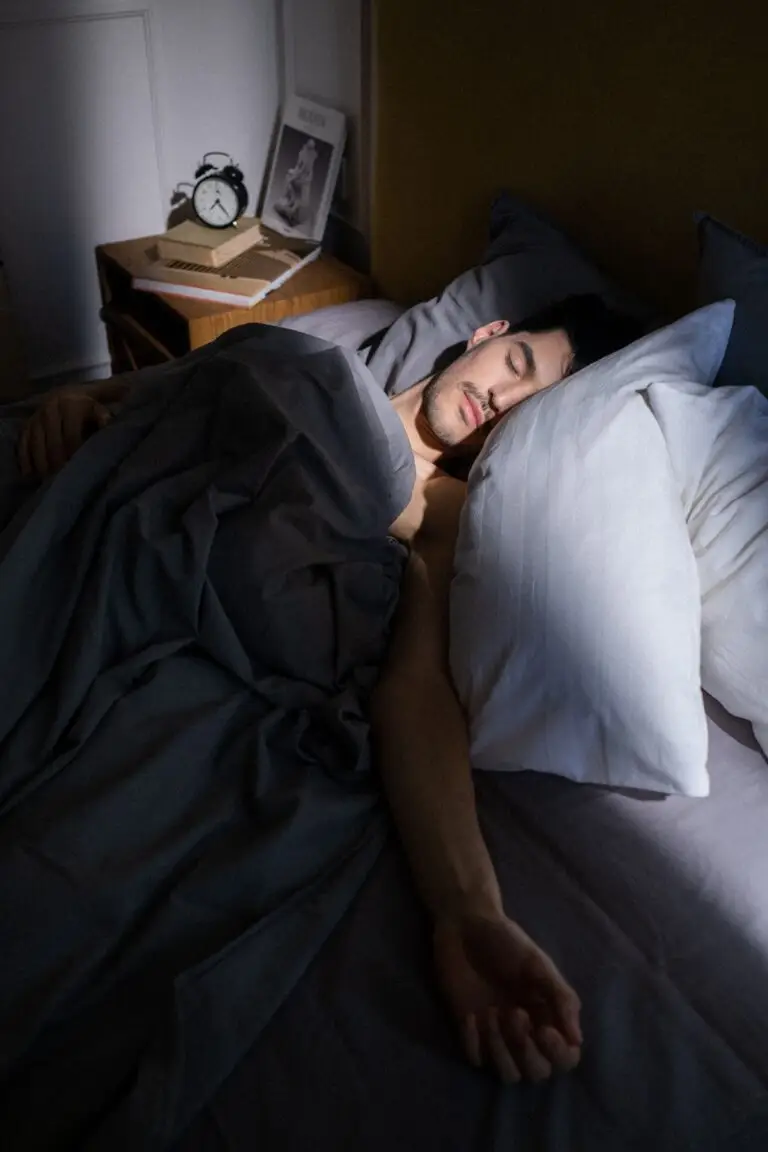
Get more sleep!
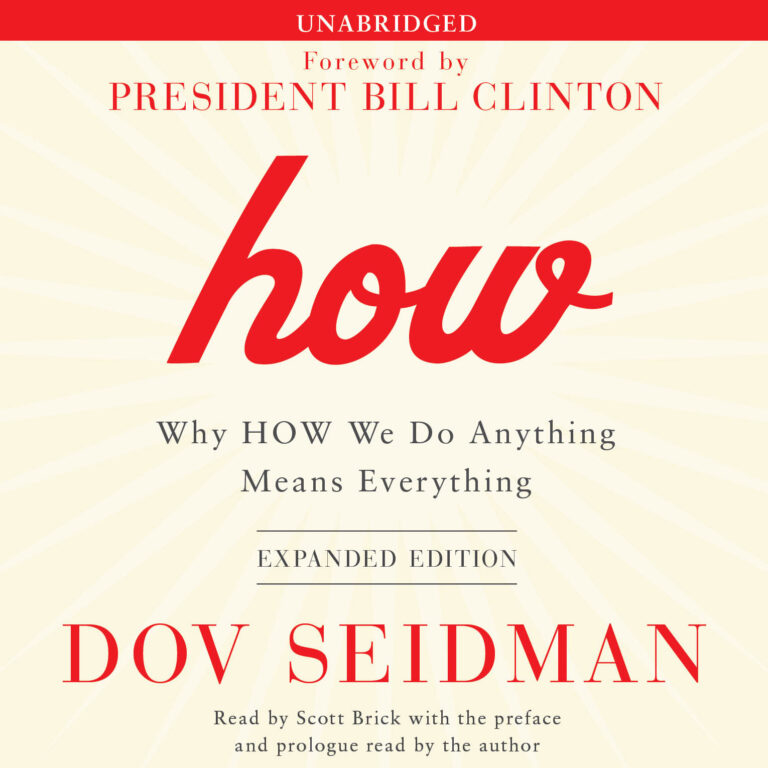
I’ve recently been reading Why We Sleep by Matthew Walker, PhD, and one of the things that caught my eye actually has nothing to do with finances. What interested me the most was that we probably don’t consciously think about how much it affects our everyday lives. From our appetite and emotional well-being, to our decision making abilities and long-term health, sleep influences more than we might realize.
So that got me thinking. If sleep influences something as simple as what we eat and how much, could it also influence how much money we spend and the way we think about our financial well-being.
Thankfully, there are researches who have had this exact same question cross their mind. While I wouldn’t say that better sleep will automatically make you wealthier, there is some compelling evidence that improving our sleep might be one of the most overlooked ways to improve your financial health.
Our Relationship with Food
Have you ever noticed that after a terrible night of sleep, you seem to be hungrier than usual? Maybe you’re craving something sugary, eating more throughout the day, or finding it harder to stick to your usual eating habits.
A 2022 randomized clinical trial published in JAMA Internal Medicine examined 80 adults who were overweight and typically slept fewer than 6.5 hours per night. Researchers divided participants into two groups. One received guidance designed to help them sleep longer, while the other continued their usual sleeping habits.
The participants who increased their sleep duration by approximately 1.2 hours per night consumed an average of 270 fewer calories per day compared with the control group. The most fascinating part about this is that the participants were not instructed to change their diets or exercise routines.
They simply worked on improving their sleep.
Now, this was a relatively small, two-week study, so we shouldn’t assume everyone would experience the same results. But if something as simple as getting more sleep can influence how much we eat, imagine how many other aspects of our daily lives might be affected by our sleeping habits.
When we consider the long-term relationship between nutrition, weight management, and physical health, those behaviors can have implications well beyond our diets.
They come for our finances.
Our Emotions
I know that after a bad night sleep, I tend to be in a bit of a pissier mood than normal. We tend to become easily frustrated, less patient, and sometimes just not in the mood to deal with anything.
A 2024 systematic review and meta-analysis published in Psychological Bulletin examined more than 50 years of research on sleep and emotional functioning. Researchers analyzed 154 studies involving 5,717 participants.
What they found was that various forms of sleep loss consistently reduced positive emotions and increased symptoms of anxiety. These effects weren’t limited to people who went an entire night without sleeping. Even partial sleep restriction and interrupted sleep could influence emotional functioning.
Something as ordinary as not getting enough sleep can change how we emotionally experience the world around us.
So what does that have to do with money? Well, a lot of our financial decisions are influenced by our emotions.
We spend money to celebrate .
We spend money when we’re stressed.
We sometimes avoid looking at our finances because we’re overwhelmed.
And we occasionally make decisions simply because we want the uncomfortable feeling associated with them to go away.
Now of course, these behaviors aren’t explicitly caused by poor sleep. But if inadequate sleep can negatively influence our emotional well-being, it’s worth considering how that might affect the way we approach our finances. Trying to make important financial decisions while you are emotionally exhausted certainly doesn’t make things easier, and I would argue it can dig you a deeper hole.
After all, financial stress is already something many people struggle with.
Healthcare
This might be the most financially significant connection of them all. Most of us are already well aware that our everyday habits influence our long-term health.
According to the Centers for Disease Control and Prevention, insufficient sleep is associated with an increased risk of several chronic health conditions, including obesity, type 2 diabetes, high blood pressure, and heart disease. And did you know that individuals identified as having insomnia had median healthcare expenditures four to six times higher than those without insomnia in matched comparison groups?
If any of us have dealt with elderly people in our lives, then we know that our health gradually decreases as we get older. Naturally, our expenses around healthcare will also go up as we age.
The one thing I’ve noticed is that most of the conversations around our health tend to focus on what we eat and our physical activity. It’s not that sleep isn’t included in those conversations, but it’s usually an afterthought, when it seems to me that it has just as important of a role to play in determining our physical and mental health.
Now I can’t conclude that simply getting more sleep will reduce someone’s medical expenses by a specific amount. Yet we spend considerably less time thinking about the everyday habits that might influence our long-term health.
As a younger person, I’ve made my fair share of decisions I knew were not the best for my body. Who hasn’t? The occasional late night or fast food meal isn’t the be all end all for your health. What’s most important is that we make the conscious effort to instill good habits as part of our daily routines; in the form of clean foods, exercise and of course, good quality sleep.
This is not me saying that getting good sleep will help you avoid medical expenses, but taking care of your health is an important part of taking care of your finances in the long run.
Improving Your Finances Isn’t Always About the Money
Here’s what I find most interesting about all of this. When people want to improve their finances, they almost always focus on solutions that directly impact that number in the bank account.
While it’s important to make decisions that will increase our incomes, cut our expenses or help us invest, we tend to overlook something important
Our financial well-being is closely connected to our overall well-being.
We don’t suddenly become completely different people when we sit down to make financial decisions. We bring our emotions, habits, stress levels, physical health, and personal experiences into every decision we make, and they trickle into our relationship with money.
I want to use this opportunity to paint a picture for you
Think of someone who is working long hours, struggling to balance responsibilities, or simply not prioritizing their sleep. Now add in the fact that they have a family with 2 kids and need to make sure that they can use some of their energy to support their loved ones. You would probably say that it sounds exhausting. Maybe you can relate because you are this person.
Making personal finance decisions doesn’t get rid of anything I brought up before. In fact, the added layer of managing expenses might overwhelm that person even more.
It’s easy to tell someone they should budget better, spend less, or invest more. Historically, we have looked at our financial well-being and our personal well-being as two separate entities. In my 8 years of experience, I’ve found that this is the wrong way to look at it. These are not two separate entities, in fact they are way more intertwined.
We can’t expect ourselves to consistently make our best financial decisions when we’re not taking care of ourselves.
That’s why improving your finances sometimes requires looking beyond your finances. It might mean improving your physical health along with your mental health.
And yes, it means probably getting more sleep.
So… How Much Should I be Sleeping?
According to the CDC’s sleep recommendations, adults between the ages of 18 and 60 should generally get at least seven hours of sleep per night.
Of course, getting more sleep isn’t always as simple as going to bed earlier. Work schedules, children, medical conditions, and stress can all make it difficult to get adequate rest.
For those of us who have some control over our sleeping habits, there are relatively simple ways to improve them.
- Maintain a consistent sleep schedule (Even on weekends)
- Avoid caffeine later in the day
- Limit electronic devices before bedtime – at least 30 minutes before
- Create a quiet & comfortable sleeping environment
If you’re consistently struggling with sleep, it may be worth speaking with a healthcare professional.
Final Thoughts
As a financial planner, I’m obviously a big believer in budgeting, saving and investing. But the more I learn about human behaviour, the more convinced I am that improving our finances requires us to look beyond the numbers.
Getting better sleep or improving our health won’t eliminate your debt or get your 401(k) to a seven-figure amount. But there is clear evidence that getting good quality sleep can influence our eating habits, our emotional well-being, decision-making and most importantly, our long-term health. All of which impact our finances one way or another.
If thinking about your finances makes you stressed out, my suggestion is that maybe you don’t need to focus on the numbers to relieve that stress. Start by taking a look at your every day habits and truthfully ask yourself if the decisions you are making are better for you both in the present and in the long run.
And maybe since you read this article, both you and I can start by going to bed a little earlier.
Disclosure
This content is provided for informational and educational purposes only and should not be construed as personalized investment, tax, or legal advice. No advisory relationship is created by reading this article. Investment advisory & financial planning services are offered only pursuant to a written agreement through Noor Financial Services, a Registered Investment Adviser. Please consult with a qualified professional regarding your specific financial situation.